Imagine a village. Not a beautiful village from a textbook, but a real one. Muddy, ancient, loud, full of animals, smoke, and people trying to survive. In this village, there is a farmer who grows wheat. There is also a weaver who makes cloth. There is a carpenter who builds furniture. And there is a fisherman who catches fish.
Every one of these people needs something the others have. The farmer needs cloth for winter. The weaver needs fish to eat. The carpenter needs wheat for bread. The fisherman needs furniture for his home. On the surface, this sounds like a perfectly functioning economy. Everyone has something, and everyone needs something. Surely it all works out.
Except it does not. And understanding exactly why it does not is the first key to understanding what money actually is.
The problem has a name. Economists call it the double coincidence of wants.
The farmer who needs cloth must find not just any weaver, but a weaver who needs wheat at the same moment, in exactly the right quantity, and who values the exchange at the same rate the farmer does. The fisherman might have a surplus of fish on Tuesday, but the carpenter only needs food on Friday, by which time the fish are no longer a bargain anyone would make.
Barter, the system where goods are exchanged directly for other goods, is slow and unscalable. It works well in very small communities where everyone knows everyone, and favours can be remembered and returned. But as communities grow, as the geographical distance between producer and consumer expands, the barter system stops being efficient.
Human beings, being the innovative creatures they are, found a workaround.
The workaround was to agree on a middleman. Not a person, but a thing. An object that everyone in the community would accept as a standard for value.
Something that could be held, transported, accumulated, and exchanged at any time, for any other good, without requiring a perfect coincidence of needs. Something that carried value not because of what it was made of, but because everyone agreed that it did.
This is the foundation of money.
It is not a commodity. It is a consensus.
Different cultures across different centuries arrived at this insight independently and chose wildly different objects to serve as this consensual store of value.
The Yap Islanders of the Western Pacific famously used enormous circular stones called Rai, some of them several feet in diameter and weighing hundreds of kilograms. These stones were so large that they could not even be moved when ownership changed hands. The entire village simply agreed that the stone now belonged to someone else, and that was enough. The record was social. The ledger was communal memory.
Elsewhere, people used cowrie shells, dried fish, bolts of cloth, cacao beans, salt, and tobacco. The specific object mattered less than the collective agreement surrounding it.
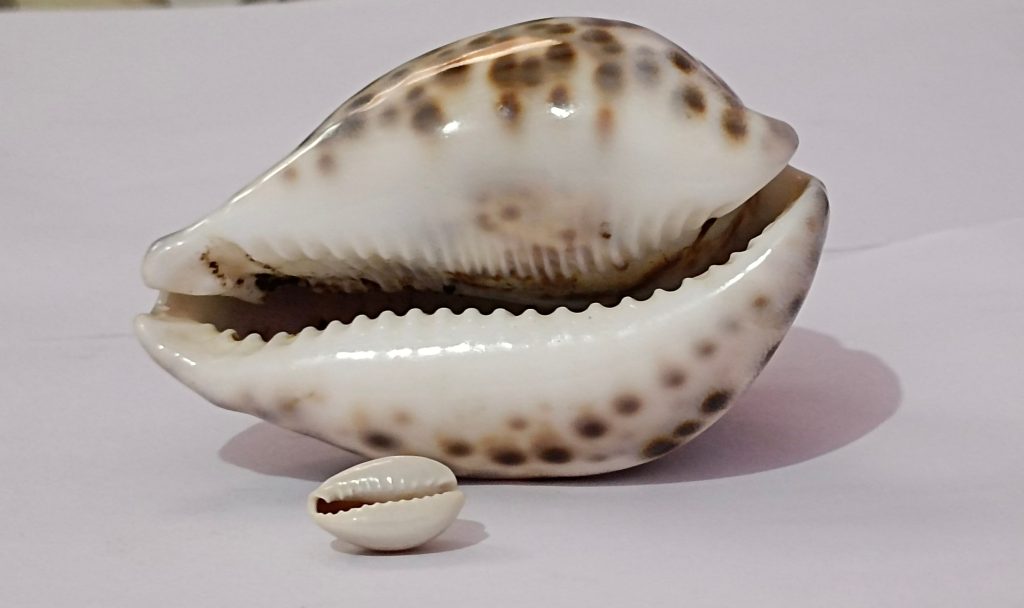
What made something money was not its intrinsic properties, but the shared belief that it would be accepted in exchange by others. Trust, in other words, was the raw material from which money was always made.
Eventually, precious metals became the dominant form of this consensual value. Gold and silver had certain practical advantages. They were rare enough to be scarce, they were durable, they did not rot or rust, and they were divisible, which meant a large piece could be cut into smaller pieces without losing proportional value. They were also portable and recognizable. Across wildly different cultures that had never been in contact, gold carried weight as a store of value.
But metals brought their own complications. How much did a particular lump weigh? Was it pure, or was it mixed with cheaper alloys? Every transaction required the metal to be weighed and tested, which was slow and created opportunities for fraud.
The solution came from a trusted third party who would take metal, assay its purity, confirm its weight, stamp it with an official mark, and guarantee its value. This was the birth of the coin, and with it, the birth of the institution that issued and guaranteed it, the very earliest form of what would eventually become the state’s authority over money. The Central Bank.
Coins were revolutionary. A stamped gold coin did not need to be weighed every time it changed hands. The coin carried with it a form of delegated trust. Instead of trusting the metal, one was now trusting the institution behind the stamp.
This subtle shift, from trusting the material to trusting the institution, is one of the most important transitions in financial history. It is the seed from which all modern money is derived.
Centuries passed. Trade routes expanded. Merchants were carrying enormous quantities of gold across vast distances, which was dangerous and expensive. The solution, when it came, was absurdly simple.
A merchant would deposit gold with a trusted goldsmith in one city, receive a paper receipt acknowledging the deposit, travel to a distant city, and present that receipt to a goldsmith there who would hand over the equivalent in gold. The receipt was not money. It was a claim on money.
Goldsmiths noticed something. People were using their receipts as payment directly, without ever going to the trouble of redeeming them for gold. If one goldsmith’s receipts were trusted, they circulated as if they were money themselves. And if the receipts circulated, that meant the gold they represented sat in the vault, largely untouched.
The goldsmith, observing this, realized something quietly extraordinary. He had more gold than anyone was likely to ask for at any one time.
He could issue more receipts than he had gold to back them, lend those excess receipts out for interest, and profit enormously, as long as no one came asking for all the gold at once.
This was the birth of banking. And it contained both enormous productive power and the seed of every financial crisis that would follow across the next several centuries.
The paper receipt that circulated as money, backed by gold stored in a vault, was the prototype of the banknote. And the goldsmith who issued more receipts than he had gold was practicing what the modern world calls fractional reserve banking.
By the time formal banks emerged and governments began issuing their own currency, the precedent was set. Paper money was a promise. It said, in effect, this note represents real value held somewhere by a trusted institution. The note itself was not the value. It was the claim.
This is a crucial distinction that most people never consciously make. The paper in a wallet, or the number on a phone screen, is not wealth. It is a symbol of a relationship. It is a ticket. And, as the twentieth century would reveal in the most dramatic way possible, the value of that ticket depends entirely on the credibility of the institution behind it.
The first chapter of the money story ends here, in the goldsmith’s vault, with a ledger full of entries and more receipts in circulation than gold to honour them. It is a system built on confidence. And the history of money that follows is, in large part, the history of what happens when that confidence is tested.