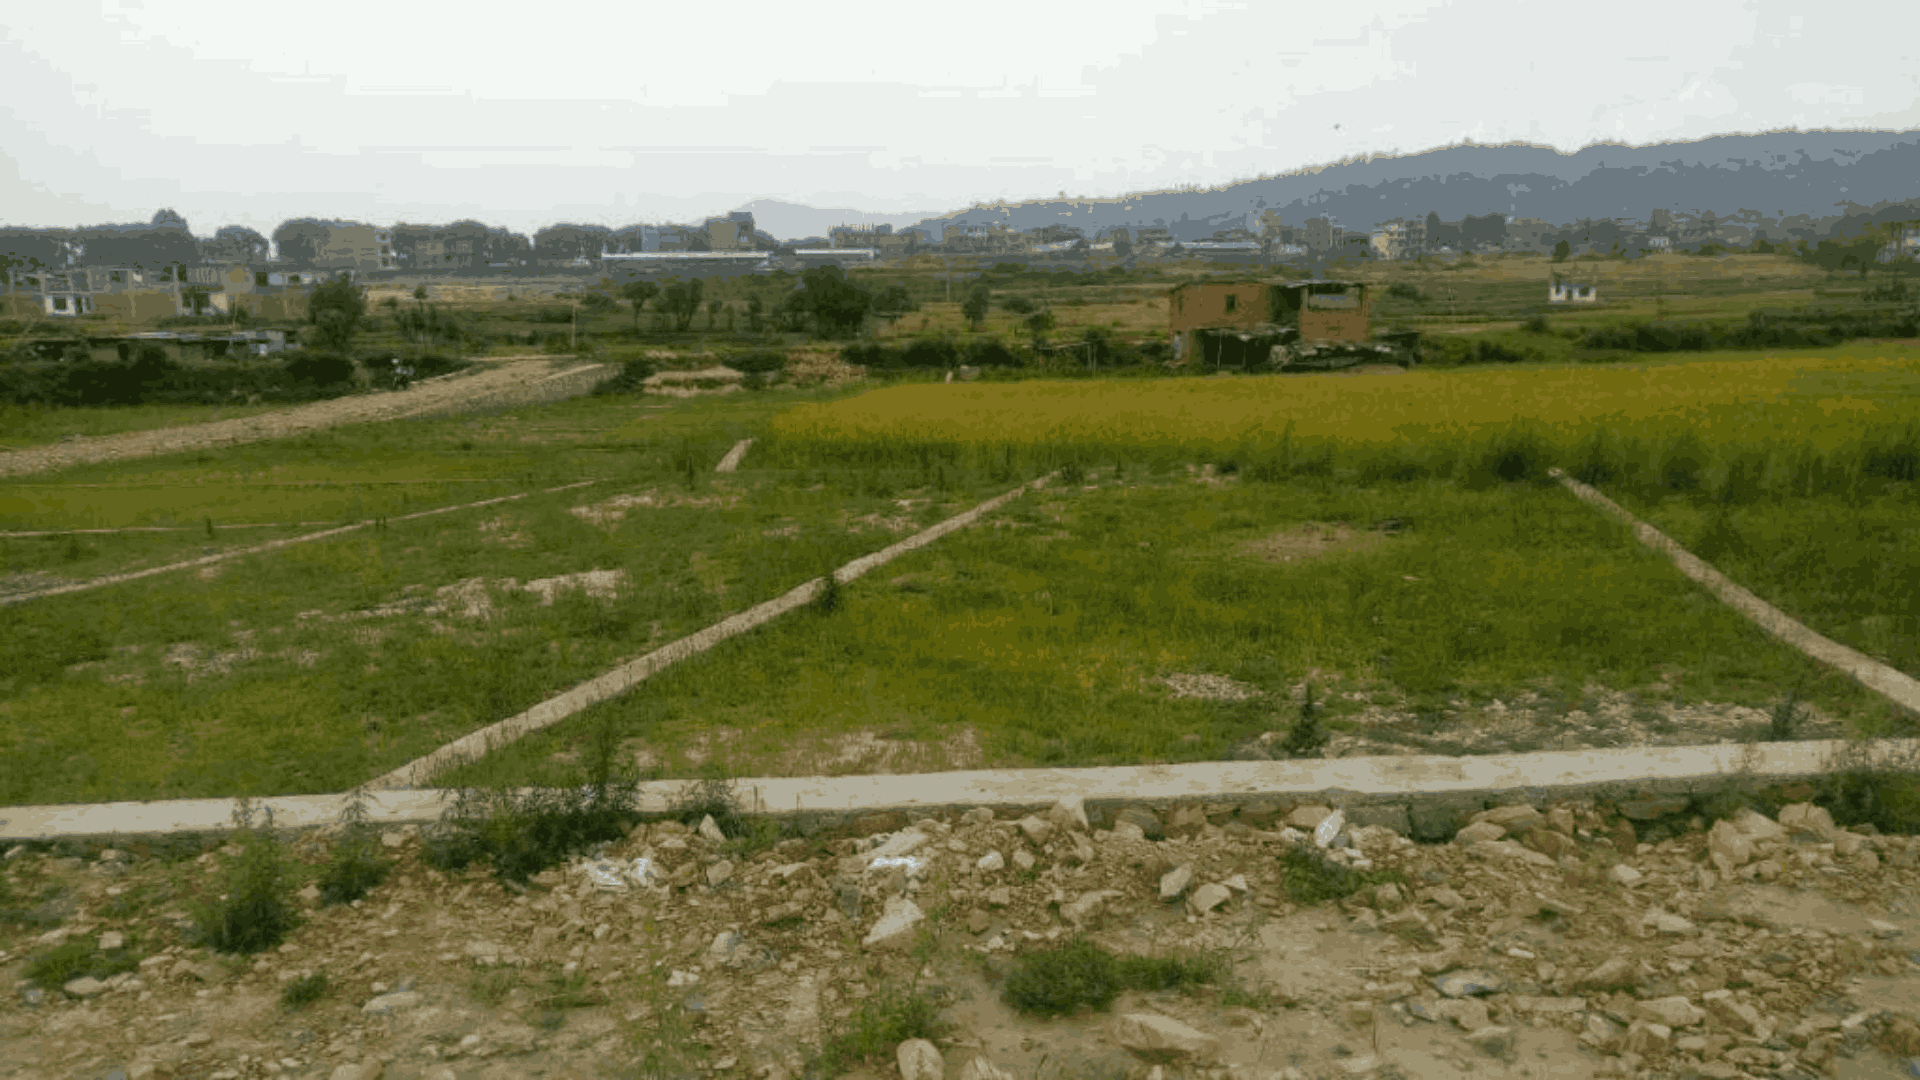
If you are an expat living in Sydney, London, or New York, you likely know the quiet anxiety of wanting to invest the money you have earned back home in Nepal, but feeling completely paralysed by the technicalities and not having someone professional to rely on.
Every single week, the same exact questions pop up: “Can I buy land directly in my own name, or do I have to trust a relative?” “Will the new NRN Citizenship change my property rights?” “How do I get my money into Nepal without getting it frozen by the central bank?”
It is time to cut through the noise, the outdated advice from ‘pailai bidesh aaunu bhayeko dai’, dead Facebook groups, and the dry legal jargon. Under modern Nepalese law, Non-Resident Nepalis (NRNs) have explicit, legally protected paths to own property directly in their own names. Yes, you can own property under your own name.
Here is your execution guide, updated for the current legal landscape. May 2026.
1. The Dangerous Myth of the “Relative’s Name”
For decades, the standard approach for expats wanting to buy real estate in Nepal was simple: wire the funds to a trusted cousin, sibling, or parent, and register the land under their name.
While done with the best intentions, buying property through a proxy is a financial ticking time bomb.
The Reality: When you buy property in a relative’s name, you hold exactly zero legal claims to that asset. If family dynamics shift, if that relative faces a lawsuit, passes away suddenly, or simply decides to leverage the asset without your permission, your life savings are completely unprotected. Nepalese courts do not recognize informal verbal agreements for real estate ownership.
Stop taking unnecessary risks with your wealth. Nepal’s updated legal framework explicitly states that foreign citizens of Nepali origin have the right to purchase land or immovable property within the country for themselves or their families. You do not need a proxy; you just need to follow the official pipeline.
2. NRN Card vs. NRN Citizenship: What Changes for Your Assets?
The legal landscape has evolved rapidly, leading to major confusion surrounding NRN identification. To secure your assets safely, you must understand the practical differences between the traditional NRN Card and the newer NRN Citizenship.
The Traditional NRN Card
Under the Non-Resident Nepali Act 2008 and NRN Regulations 2066, a Foreign Citizen of Nepali Origin (FCNO) can obtain an NRN Identity Card valid for 10 years. This card serves as your primary legal vehicle to buy land, open foreign currency bank accounts, and manage domestic investments.
The New NRN Citizenship Certificate
The Nepal Citizenship (Third Amendment) Regulations formally operationalized the NRN Citizenship Certificate (गैरआवासीय नेपाली नागरिकता). While this grants historic economic, social, and cultural rights, it is crucial to understand its boundaries regarding real estate.
Does NRN Citizenship grant unlimited land purchases? No. Whether you hold a 10-year NRN Card or an NRN Citizenship, you are still bound by strict legal land ceilings when acquiring new residential real estate.
What about ancestral property? This is highly protected. Under the National Civil Code 2074, ancestral wealth and inherited property transfer seamlessly to legal heirs holding NRN status.
Legacy Assets: If you acquired property in Nepal before giving up your Nepali citizenship, those legacy assets are completely exempt from NRN ceilings. They remain protected under your historical citizenship rights.
3. The Strict Legal Land Ceilings (Exactly How Much You Can Buy)
To manage market speculation, the NRN Regulations 2066 dictate precise maximum caps on how much real estate an NRN can purchase for personal or family residence.
Before shortlisting a property, ensure it fits within these legal boundaries:
| Region / Location | Maximum Permissible Land Ceiling |
| Kathmandu Valley | Up to 2 Ropanis |
| Terai District Municipalities | Up to 8 Katthas |
| Terai Rural Areas (Gaunpalikas) | Up to 1 Bigha |
| Other District Municipalities | Up to 4 Ropanis |
| Any Other Regions | Up to 10 Ropanis |
The Inheritance Loophole
If you inherit ancestral property that happens to exceed these limits, you do not have to surrender it. The law explicitly protects property that was lawfully acquired while you were still operating in the capacity of a full Nepali citizen. The ceilings only restrict new commercial or residential acquisitions made after taking foreign citizenship.
4. The Banking Flow: Validating Your Source of Funds
Finding the right plot of land or apartment is only 20% of the battle. The remaining 80% comes down to banking compliance. If you mismanage the cash flow, your property registration will be blocked, and your funds can be frozen under anti-money laundering protocols.
[ Informal Channels / Hundi ] ➔ Flagged by NRB ➔ Transaction Blocked & Funds Frozen
[ Official Banking Route ]    ➔ Issued FIRC     ➔ Smooth Malpot Registration (Approved)
Under Nepal Rastra Bank (NRB) Directives, all inward capital meant for property acquisition must be executed in convertible foreign currency via formal banking networks.
To ensure a seamless transaction, follow this exact compliance path:
Open the Correct Account Type: You must route the money through a designated NRN Foreign Currency Account or an official Remittance Account registered in your name at a licensed Class “A” commercial bank in Nepal.
Pass Anti-Money Laundering (AML/CFT) Checks: You will be required to fill out a comprehensive self-declaration form verifying the legal source of your foreign wealth (tax returns, employment slips, or business revenue overseas).
Secure Your FIRC: Once your wire transfer clears, request a Foreign Inward Remittance Certificate (FIRC) from your bank. This single document is your golden ticket. It proves to the Land Revenue Office that your money enters the country cleanly and legally.
5. Step-by-Step: The Purchase Pipeline from Abroad
When you are ready to pull the trigger on a property purchase from overseas, execute this precise four-step checklist:
Step 1: Secure Your NRN Credentials
Before signing any sales agreements, register formally as an NRN. Submit your foreign citizenship records and proof of your original Nepali roots to your nearest Nepalese Embassy or Consulate to secure your NRN Card or NRN Citizenship.
Step 2: Route the Funds and Grab the FIRC
Wire the exact purchase amount directly from your overseas bank account to your NRN account in Kathmandu. Avoid using third-party money transfer apps or intermediaries. Ensure your bank flags the deposit specifically for property purchase and secures the FIRC immediately upon arrival.
Step 3: Secure Ministry Approval
Unlike a local buyer, an NRN transaction requires an extra administrative step. You must submit a formal application to the Secretary of the Ministry of Land Management. The application must outline the exact plot number, location, total area, and agreed valuation. The Ministry verifies that the property complies with the geographic land ceilings before granting an official clearance letter.
Step 4: Register the Blue Lalpurja
Take your Ministry approval letter, your FIRC, and your NRN credentials to the local Land Revenue Office (Malpot). Once the registration fees and taxes are settled, the government will officially register the land in your name. As an NRN, you will be issued a distinct, blue-colored Land Registration Certificate (Lalpurja), cementing your absolute legal ownership over the asset.
6. Take Control of Your Legacy Back Home
The legal framework is fully in your favor. You no longer need to rely on high-risk proxy arrangements or stress over family disputes. As a Non-Resident Nepali, your right to invest in and hold property in Nepal is entirely protected by law.
However, knowing the law is very different from executing it smoothly. Navigating Malpot offices, drafting ironclad fund routing pathways, passing central bank AML clearings, and securing your blue Lalpurja requires absolute technical precision. A minor clerical mismatch or an unverified banking source can delay your transaction or lock up your capital for months.
You have worked too hard building your life abroad to leave your investments back home to chance.
Stop guessing, and protect your wealth with professional certainty.
Let’s look at your numbers together. Click below to schedule a private, one-on-one consultation. I will audit your source of funds, structure your international banking flow, and execute your real estate purchase with zero legal blind spots.